Our Client was weighing an investment in an authorized contact-centre technology solutions provider operating across Pakistan, the UAE and Bahrain. We performed buy-side financial due diligence to show what the business was really earning, and what that meant for its value.
- Location
- Pakistan, UAE and Bahrain
- Sector
- IT Services
The Brief
The Client asked us to assess the target's quality of revenue and quality of earnings for the period from FY 2024 to CY 2025.
We were also to review its contracts and establish whether any contained a termination clause that would be triggered by a change in management.
The Obstacle
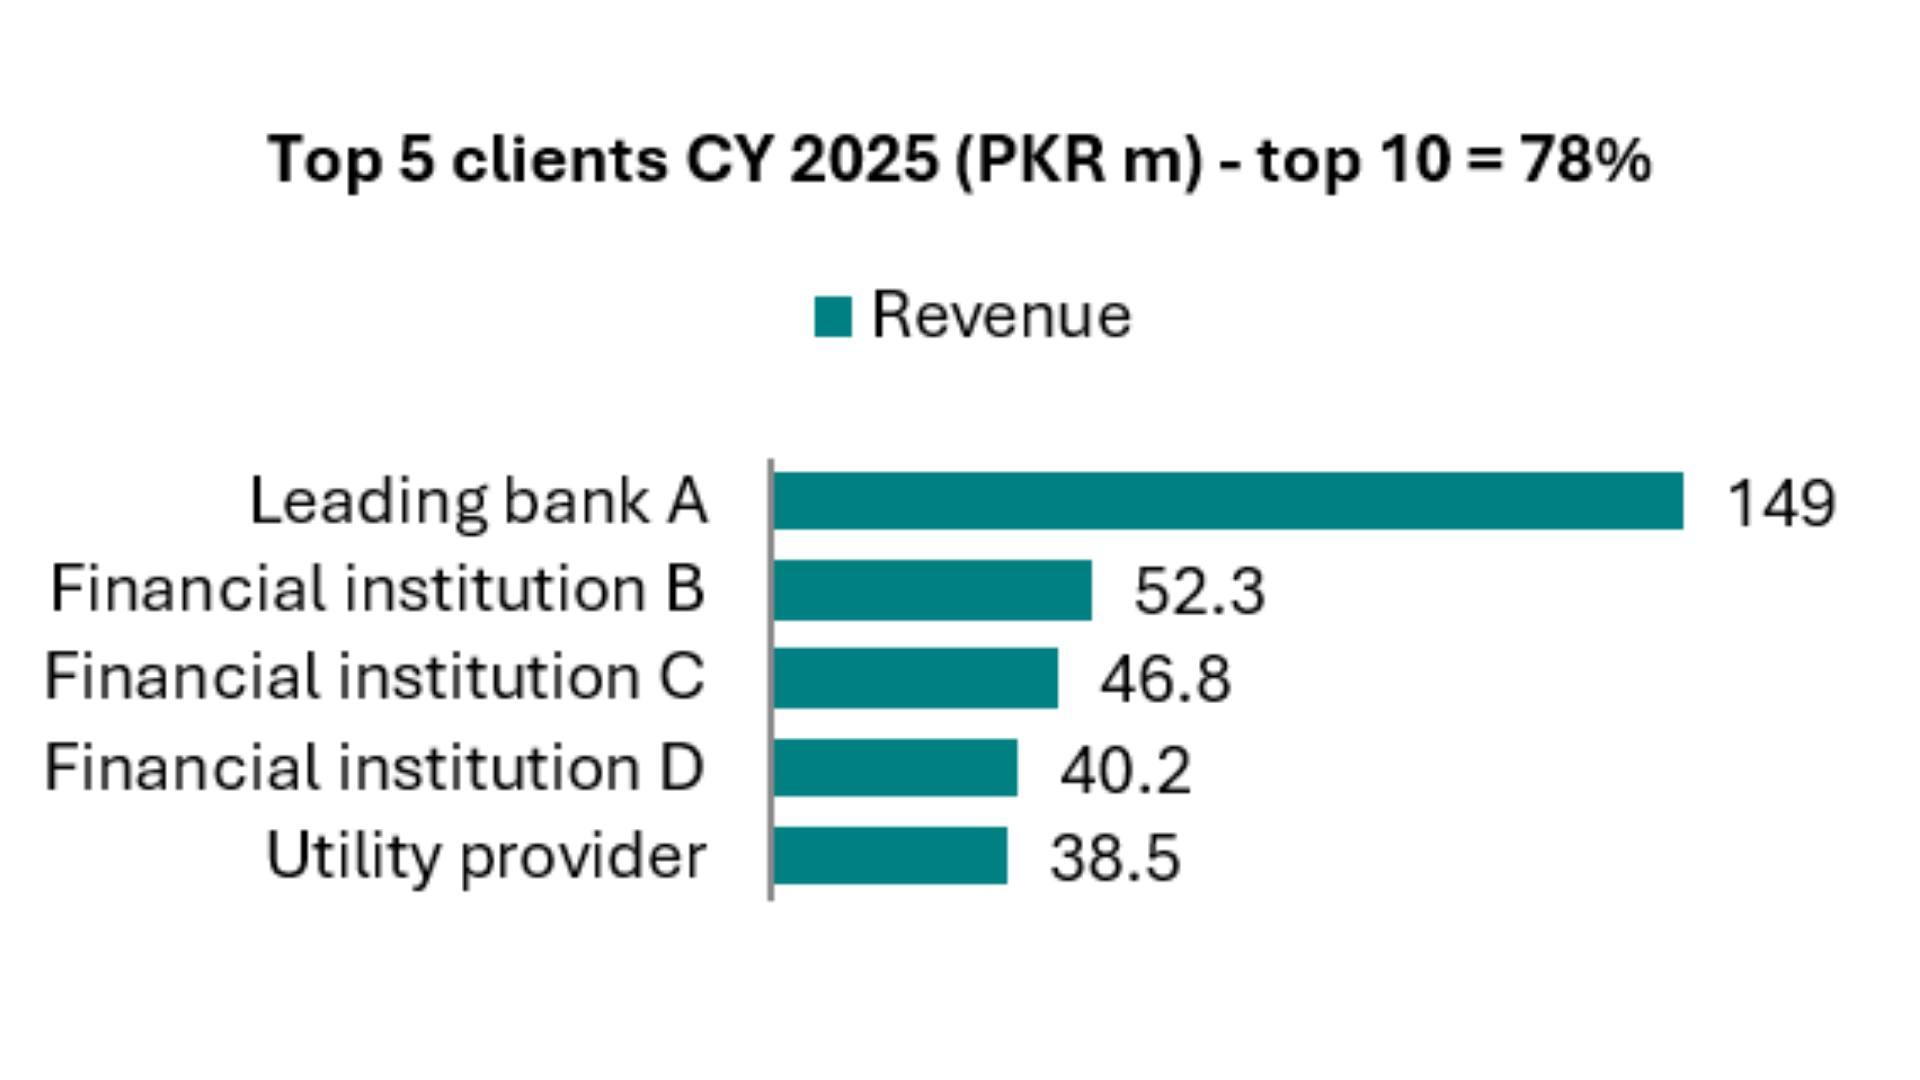
Revenue was highly concentrated, with the top 10 clients contributing 78% of the total. A leading bank then terminated its agreement in December 2025, taking that amount out of recurring revenue.
The accounts also needed correcting. Inter-company vendor transfers had been invoiced as sales, and a disputed payable had not been recorded.
Our Approach
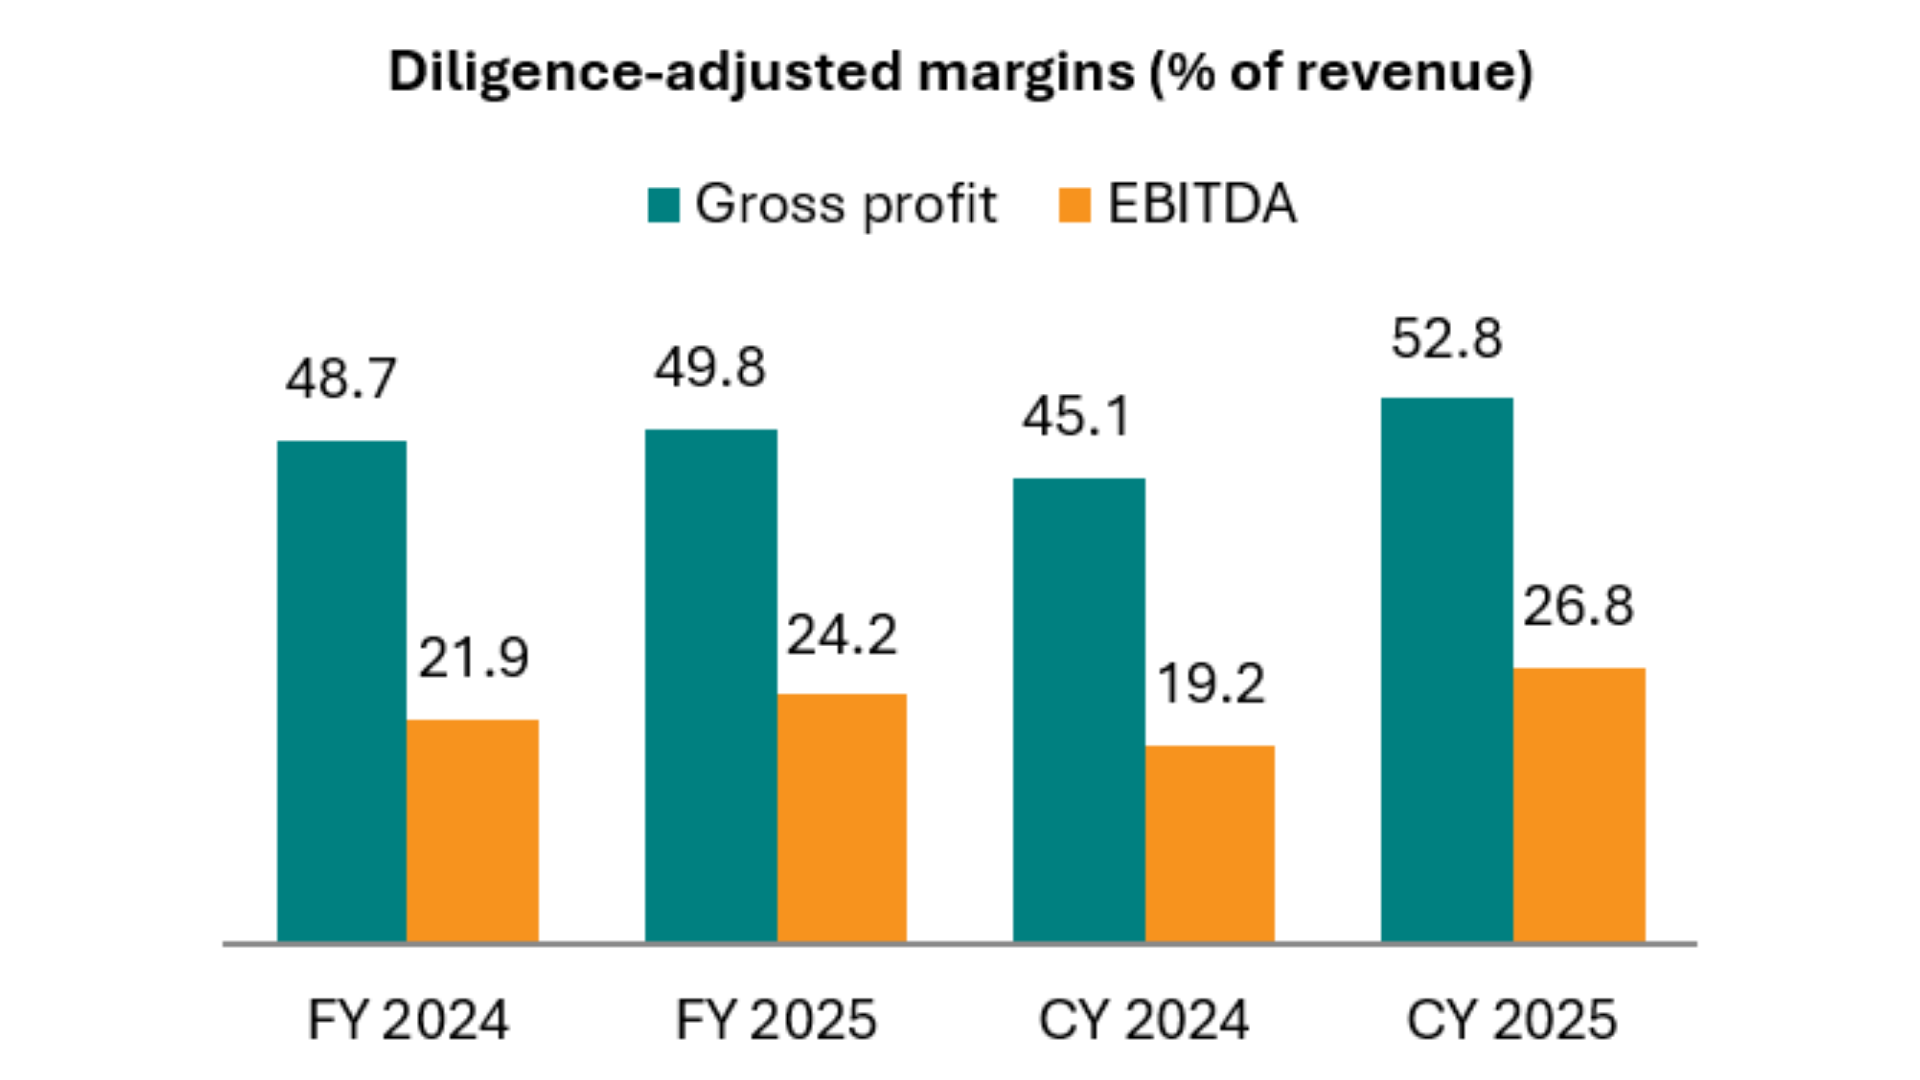
We rebuilt the target's earnings from the ground up, normalizing them for terminated contracts, misclassified sales and one-off costs so the numbers reflected the business the Client would actually be buying.
We then carried those findings through to working capital, cash and the equity valuation, and reviewed the contracts for change-of-management risk to inform the shareholders' agreement.
What We Delivered
Quality of revenue and quality of earnings reports with normalization adjustments, normalized working capital and minimum operating cash analyses, and an excess cash schedule, equity valuation bridge and SHA considerations.
78%of revenue traced to the top 10 clients
3normalization areas: terminated contracts, misclassified sales and one-off costs
Our Impact
The Client received a diligence-adjusted equity valuation reflecting the key commercial and financial risks.
Revenue and contingency risks were quantified, giving the Client a clear basis for price negotiations, and the key SHA considerations we identified supported an informed investment decision.